By a disabled U.S. Army veteran

Buy the land first.
Build the house second.
Without a lender telling you no.

Every lender says the VA doesn't do land loans. That's the front-desk answer. The real answer is four financing stacks that let a vet actually end up owning rural acreage — and I put every one of them in one 50-page playbook.

30-day money-back guarantee Instant PDF download Free updates for life
Complete bundle $27
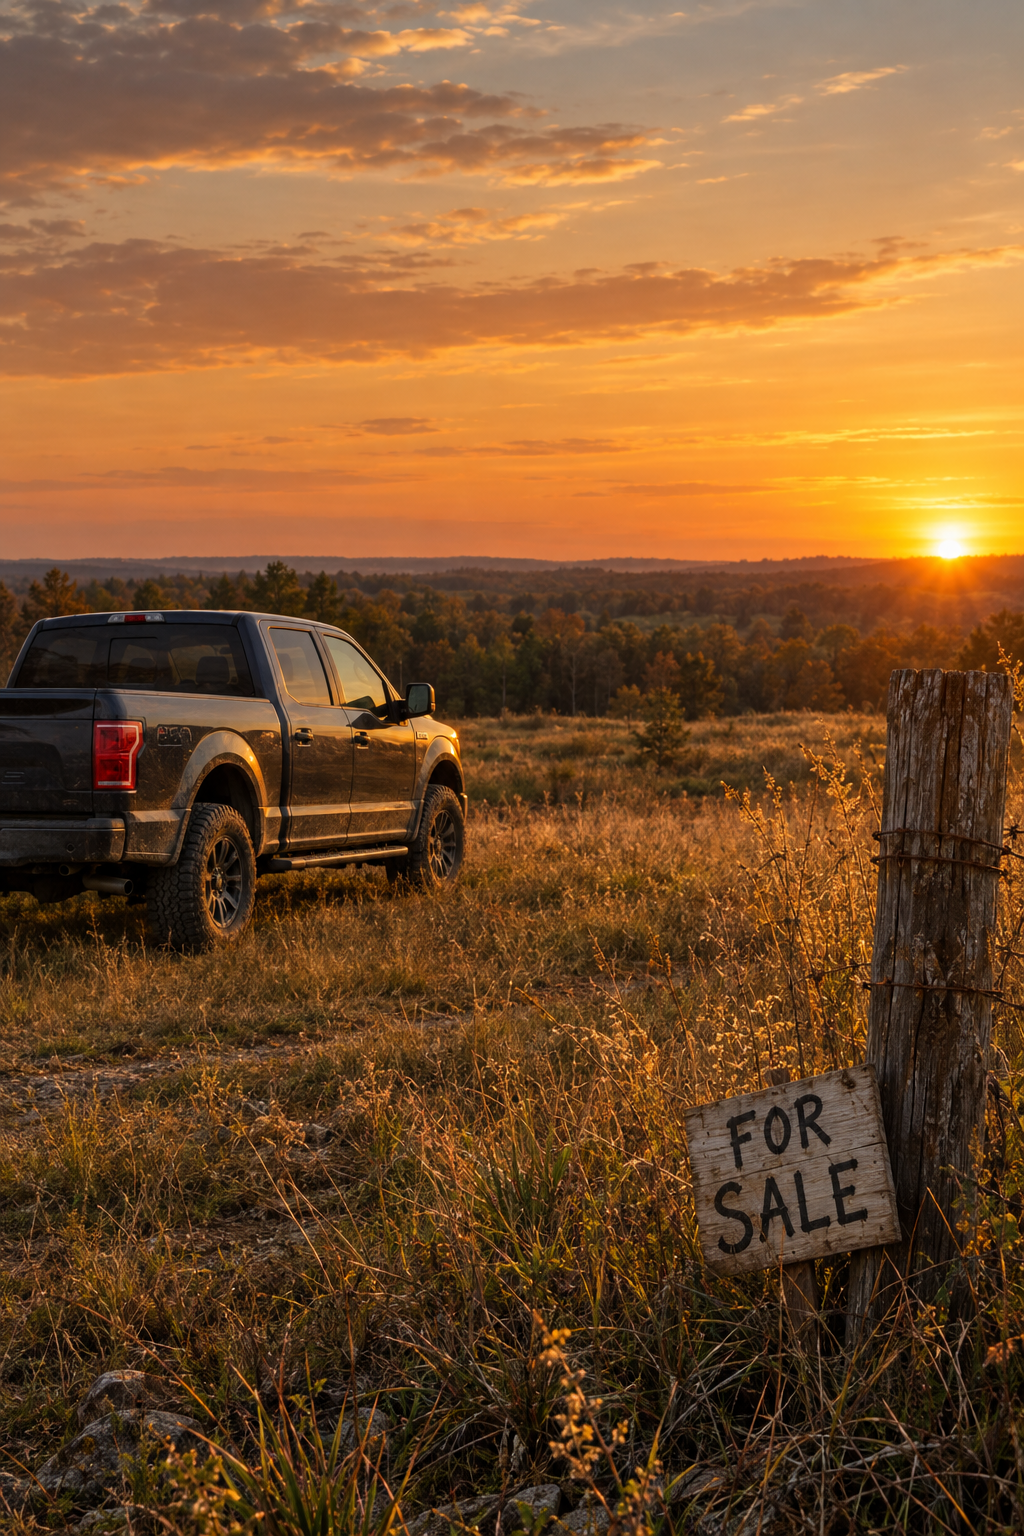
Sunset over rural acreage with a FOR SALE sign along a country road — cover of the Land Before House playbook.

The lie you keep hearing

Four lenders. Same answer. All wrong.

I called four different lenders about buying rural acreage with my VA loan. Every single one told me some version of the same thing. Then I actually did the research. Here's what I found.

The VA doesn't do land loans.
Lender #1 — regional bank
You'd need to already have a house on it.
Lender #2 — big-box mortgage co.
Try a farm credit union.
Lender #3 — online broker
Nobody does that anymore.
Lender #4 — national brand
The truth

There are four real financing stacks. This playbook covers every one.

Most loan officers have never done a construction loan. Most vets have never heard of USDA 502. And the sellers offering owner financing get you into paperwork that can cost you the land and the down payment if you don't know what to sign.

01

VA construction loans

Single-close and two-time close options with the short list of lenders who actually do them in 2026. Veterans United, New American Funding, Mountain America, Cornerstone, Navy Federal, and the regional credit unions serving military bases.

→ Skip the "we don't do that" front desks
02

USDA Section 502

Direct and Guaranteed programs, plain-English. The Direct subsidy that can drop your effective rate as low as 1%. Guaranteed income caps up to 115% AMI. And why VA disability comp actually helps you qualify.

→ Rates as low as 1% if you qualify
03

State veteran land programs

The Texas Veterans Land Board — the only true vet-buys-land loan in America. $200,000, 5% down, 7.25% fixed, 30 years. Plus Cal-Vet, Oregon ODVA, and how to find your own state's program.

→ Texas: $200k at 5% down
04

Owner financing (seller carry)

Skip the bank entirely — 10 to 20% down, 6 to 10% rates, structured with a deed of trust (never a land contract). Plus the refi-into-VA/USDA endgame that turns owner financing into a real path to ownership.

→ No bank approval needed
What you get

Five files. One bundle. Delivered instantly.

Everything I wrote for myself as a disabled Army vet actually trying to buy rural acreage — cleaned up and organized so another vet can skip the runaround.

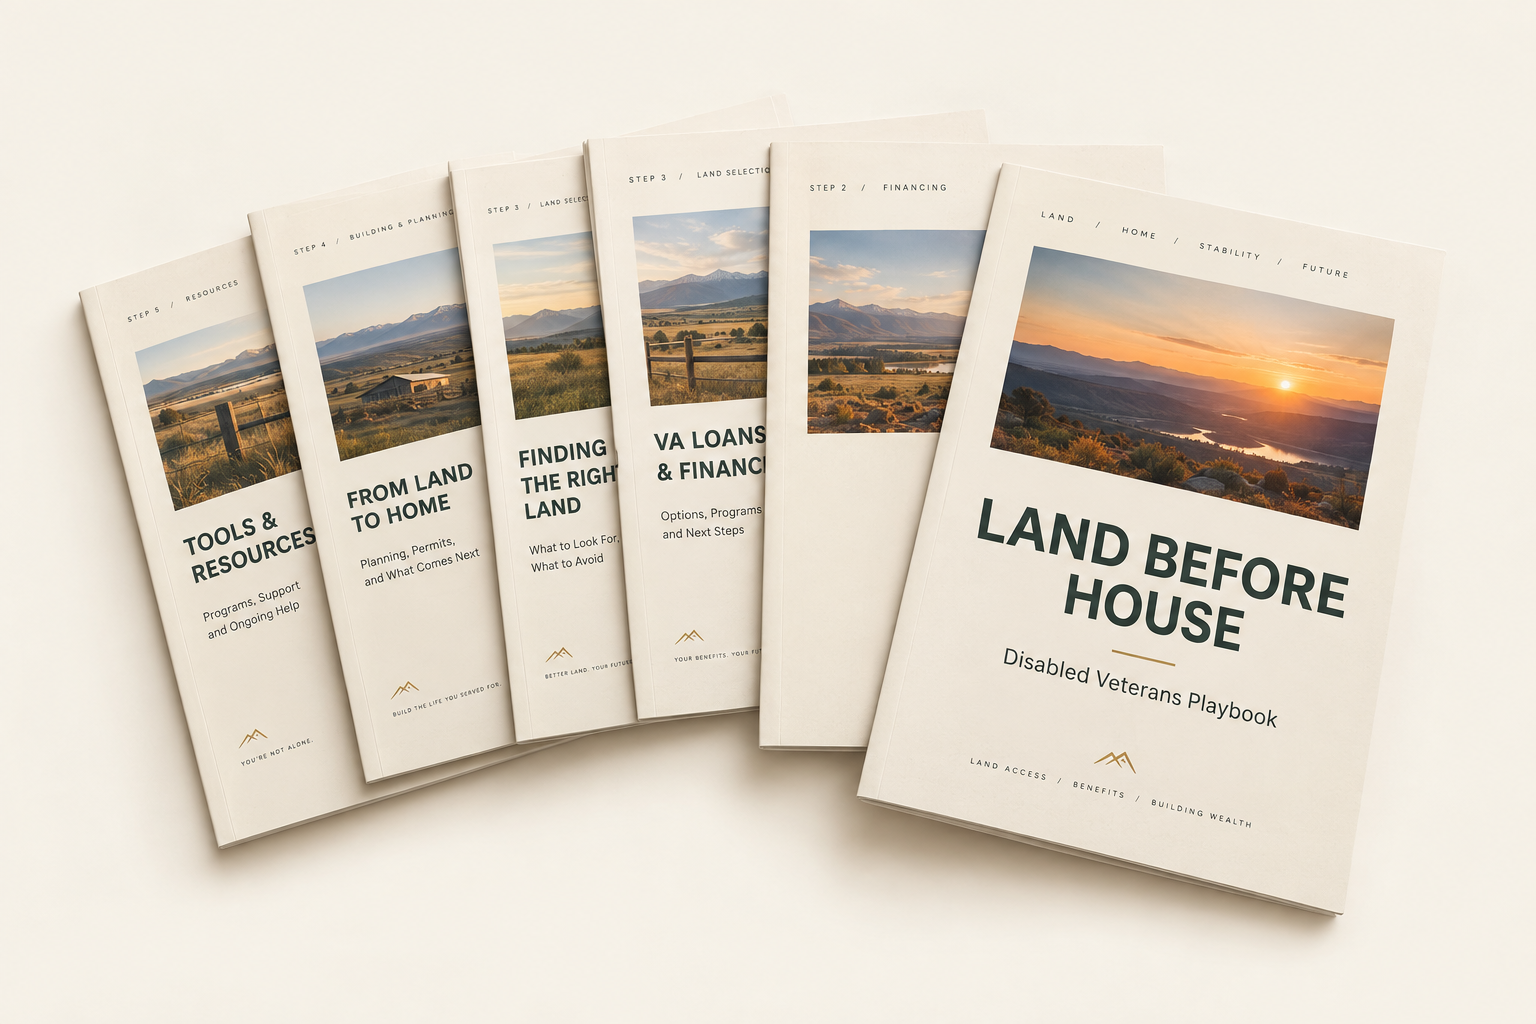
The Land Before House bundle — five PDF documents fanned out on a warm cream background.
Land Before House — Complete Bundle

The Disabled Veteran's Playbook for Buying Rural Acreage

  • The main guide. 50+ pages, all four financing stacks with plain-English breakdowns and 2026 numbers.
  • 10 lender phone scripts. Copy, paste, edit. Get past the "we don't do that" front-desk reps in one call.
  • 47-point due diligence checklist. Printable. Every item you must verify before signing on rural land — title, perc, easements, all of it.
  • Owner-financing offer letter. Fill-in-the-blank template with the six key terms, contingency language, and buyer-protective structure.
  • Notion tracker setup. Free 5-database workspace to run your entire land purchase end-to-end. 20-minute setup.
$27
One-time.
Instant download.
30-day money-back guarantee. Email me — I'll refund you.
Who wrote this

Josh Kaiser

I'm a disabled U.S. Army veteran currently trying to buy acreage in Southern Humboldt County, California, from my home base in Spring, Texas. I wrote this because I couldn't find it anywhere else and I got tired of paying the confused-vet tax.

No affiliate links. No lender kickbacks. No "as-a-service" upsell. Just the map I wish someone had handed me on day one, priced so any vet can afford it.

— Josh

Common questions

Questions I got before you asked them

Does this apply outside of Texas?

Yes — the four financing stacks (VA construction, USDA 502 Direct and Guaranteed, state programs, and owner financing) work nationwide. The Texas VLB chapter is Texas-specific, but I also cover Cal-Vet, Oregon ODVA, and how to find your own state's program if you're anywhere else.

I'm not disabled — is this still useful?

Yes. Everything in the playbook applies to any veteran with an active VA entitlement. The disabled-vet angle just means a few extra advantages I call out — waived funding fees, better USDA treatment, and how disability comp counts as stable income for underwriting.

Am I really going to save more than $27?

The lender phone scripts alone can save you a week of dead-end calls. The 47-point checklist can save you from buying land with a failed perc test or severed mineral rights — mistakes that cost tens of thousands to unwind. The owner-financing offer letter can save you months of back-and-forth negotiation. If none of that saves you at least $27, email me and I refund you, no questions.

Is this legal or financial advice?

No — and the guide says exactly that in the intro. I'm not a licensed loan officer or an attorney. This is a vet-to-vet playbook. Verify every number and every piece of paperwork with your lender, your VA regional office, and a real estate attorney in your state before you sign anything.

What if I can't afford $27 right now?

DM me on Reddit or hit reply on any of my emails. If you're an active vet trying to buy land, I'll send you a copy for free. This isn't going in a vault.

Do I get updates when the playbook is revised?

Yes — every buyer gets free updates forever. When I ship v2, v3, and beyond, you just log into your Gumroad account with the same email and download the new version at no extra cost.

How is this delivered?

Instant PDF download after checkout. Five files bundled into one ZIP. Read them on your phone, laptop, or print the checklist and take it to the property visit.

Not ready to buy yet?

Get the free VA land loan truth sheet.

Two pages, three minutes to read. The 60-second version of what every lender should tell you about VA and USDA loans for rural land — but doesn't. Free.

One playbook. One decision.

Stop letting front-desk reps decide whether you can own land.

You served. You have the entitlement. You have the disability rating. You have the credit. The only thing standing between you and rural acreage is a map — and I already drew it.

Get the bundle for $27

30-day money-back guarantee · Instant download · Free updates for life